In this guide11 sections
- Key takeaways
- How spinal cord injuries happen at work
- Benefits available after a spinal cord injury
- When a spinal cord injury counts as 100% disability
- Life pensions for ratings of 70% or more
- Lifetime medical care and home care
- Common insurer arguments in spinal cases
- Settling a spinal cord injury claim
- Lawsuits against outside parties
- Frequently asked questions
- Talk to a California workers’ comp lawyer
A spinal cord injury at work can qualify you for California workers’ comp benefits that last the rest of your life. Medical care for the injury can continue for life, and if the injury leaves you with practically total paralysis, the law presumes you are 100% permanently disabled, which means weekly payments for life. Because these claims are so valuable, insurers often contest the medical evidence, so the details of your case matter.
Key takeaways
- An injury resulting in practically total paralysis is conclusively presumed to be a permanent total disability (Labor Code §4662).
- Permanent total disability is paid for life, and for injuries on or after January 1, 2003, those payments increase each January 1 (Labor Code §4659).
- Ratings of 70% to 99% earn a life pension after the regular permanent disability payments end.
- Medical treatment reasonably required for the injury, including home health care when prescribed, is covered (Labor Code §4600).
- If someone other than your employer caused the injury, you may also have a civil lawsuit, generally due within two years.
How spinal cord injuries happen at work
Workplace spinal cord injuries usually come from high-force events:
- Falls from ladders, roofs, scaffolding or loading docks
- Vehicle and forklift crashes while working
- Falling loads, collapsing shelving or being struck by equipment
- Machinery accidents and crush injuries
- Assaults on the job
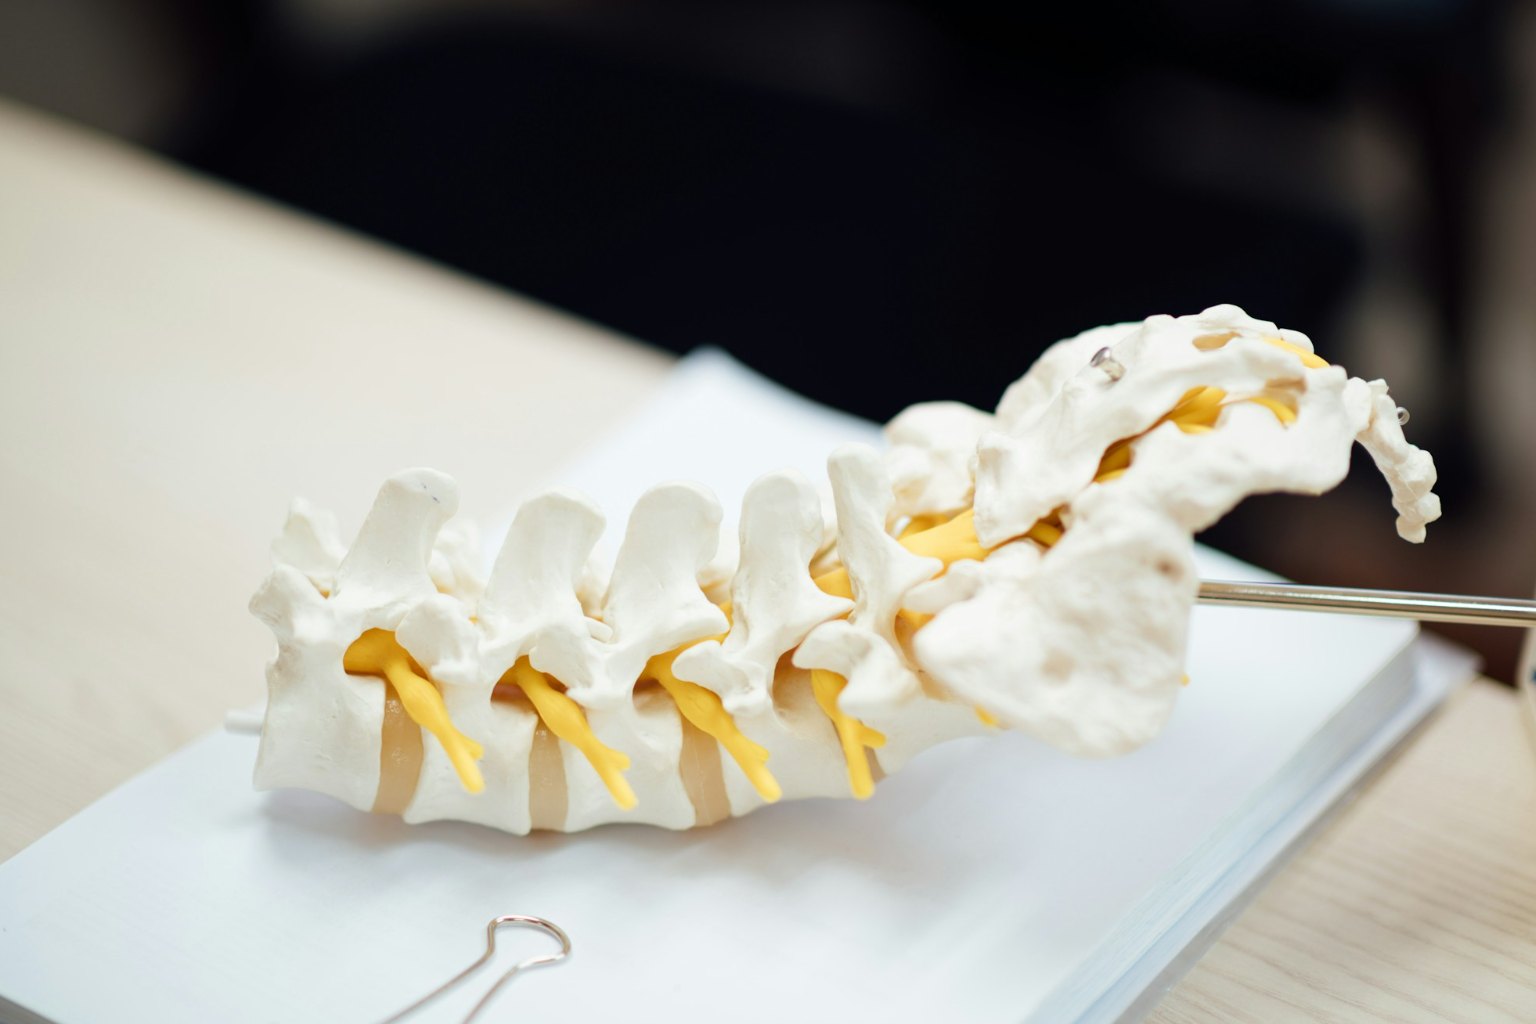
Spinal injuries range widely. An incomplete injury leaves some feeling or movement below the injury; a complete injury doesn’t. Injuries in the neck can cause tetraplegia (quadriplegia), and lower injuries can cause paraplegia. Many workers also suffer vertebral fractures, herniated discs and nerve root damage without cord injury. Each type is rated differently for permanent disability.
Your own mistake generally doesn’t bar benefits, because workers’ comp is paid without regard to fault (Labor Code §3600), and an injury while driving or working away from the main jobsite can still be covered if you were doing your job.
Benefits available after a spinal cord injury
| Benefit | What it provides (as of 2026) |
|---|---|
| Medical treatment | Surgery, hospital and rehab care, medicines, therapy, equipment and devices, and home health care when reasonably required and prescribed, for as long as needed for the work injury |
| Temporary disability | Two-thirds of your average weekly wages, between $264.61 and $1,764.11 a week, generally for up to 104 weeks within five years of the injury |
| Permanent partial disability | Weekly payments based on your rating; ratings of 70% to 99% add a life pension |
| Permanent total disability | Payments for life, with annual increases for injuries on or after January 1, 2003 |
| Job displacement voucher | $6,000 for retraining if your employer doesn’t offer suitable work (injuries on or after January 1, 2013), plus a possible one-time $5,000 Return-to-Work Supplement |
| Death benefits | $250,000 to $320,000 for total dependents, plus up to $10,000 for burial |
The temporary disability limits are from the Division of Workers’ Compensation’s 2026 announcement; the voucher rules are on DWC’s supplemental job displacement benefit page. You can estimate your weekly rate with our free workers’ comp benefits calculator.
When a spinal cord injury counts as 100% disability
Labor Code §4662 lists injuries that are conclusively presumed to be total permanent disability, including an injury that results in practically total paralysis. “Conclusively presumed” means the insurer can’t argue the rating down with a lower medical rating. For other spinal injuries, total disability is determined “in accordance with the fact,” usually through medical evidence and, often, vocational evidence showing you can’t compete in the open labor market.
Permanent total disability is paid for the rest of your life based on your average weekly earnings, and for injuries on or after January 1, 2003, the payments rise each January 1 in line with the state average weekly wage (Labor Code §4659(b), (c)). Read more in our guide to permanent total disability.
Life pensions for ratings of 70% or more
If your rating is at least 70% but under 100%, you receive the regular permanent disability payments and then a life pension (Labor Code §4659(a)). The pension equals 1.5% of your average weekly earnings for each percentage point above 60%, and for injuries on or after January 1, 2006, the average weekly earnings used are capped at $515.38.
Here is a hypothetical. Rafael, a roofer, falls and suffers an incomplete spinal cord injury that leaves him able to walk short distances with braces. His final rating is 80%. Assuming his wages were above the cap, his life pension would be 20 points × 1.5% = 30% of $515.38, or about $154.61 a week, beginning after his regular permanent disability payments end, with annual increases. If his injury had left him with practically total paralysis, he would instead be presumed 100% disabled.
Lifetime medical care and home care
The insurer must provide treatment reasonably required to cure or relieve the effects of the injury (Labor Code §4600), and that obligation can continue for life. For spinal cord injuries that can mean surgery, inpatient rehabilitation, wheelchairs and other equipment, bladder and bowel care, pain management, psychological care and home health care. Requests go through utilization review, and denials can be challenged through independent medical review.
Home health care must be reasonably required and prescribed by a doctor, and care by a family member can sometimes be paid. See will workers’ comp pay a family member for home health care?
If you develop depression or anxiety after a catastrophic injury such as paralysis, the psychiatric condition can add to your permanent disability rating, an exception to the usual rule for injuries on or after 2013 (Labor Code §4660.1(c)).
Common insurer arguments in spinal cases
- “It’s degenerative.” Insurers often blame prior disc disease. Permanent disability can be apportioned to other causes only when a doctor addresses causation and states approximate percentages (Labor Code §4663), and those opinions can be challenged.
- “You can do some work.” For a non-paralysis injury, the question is whether you can actually compete for work. Vocational experts often address this.
- “This treatment isn’t necessary.” Treatment denials go through utilization review and independent medical review.
- “The medical-legal report says otherwise.” You can object to and challenge a QME or AME report. See how to dispute a QME or AME report.
Settling a spinal cord injury claim
Serious spinal cases can end with a stipulated award, which keeps lifetime medical care open, or a compromise and release, which closes future medical care for a lump sum. A judge must approve either one (Labor Code §5001). If you are on Medicare or likely to qualify soon, a settlement that closes medical care may need to account for Medicare’s interests; see our Medicare set-aside guide.
Lawsuits against outside parties
Workers’ comp is generally your only remedy against your employer, but you can also sue a third party whose negligence or defective product caused the injury, such as another driver, a ladder or harness manufacturer, or another contractor on the site (Labor Code §3852). These claims can pay pain and suffering and full lost earnings, and they generally must be filed within two years (Code of Civil Procedure §335.1). The comp insurer can usually be reimbursed from that recovery.
Frequently asked questions
Am I automatically 100% disabled if I’m paralyzed?
If the injury results in practically total paralysis, Labor Code §4662 conclusively presumes permanent total disability. Partial paralysis or other spinal injuries are rated on the medical and vocational facts.
Do lifetime payments increase over time?
For injuries on or after January 1, 2003, permanent total disability payments and life pensions increase each January 1 based on changes in the state average weekly wage.
Will workers’ comp pay to modify my home or vehicle?
Coverage depends on whether the item is reasonably required to cure or relieve the effects of your injury. Requests should come from your treating physician and go through the insurer’s review process.
What happens when temporary disability runs out?
Temporary disability generally ends after 104 weeks within five years. Permanent disability payments then become the main source of indemnity, so ratings and timing matter.
Can I still get benefits if I wasn’t careful?
Generally yes. Workers’ comp is no-fault, with narrow exceptions such as intoxication or intentionally self-inflicted injury.
Talk to a California workers’ comp lawyer
Employees First Labor Law represents workers exclusively in workers’ compensation and employment cases across California, including catastrophic injury claims. We offer free virtual consultations. Contact us online or call (310) 853-3461.
This article is general information about California law as of 2026, not legal advice for your situation. Reading it does not create an attorney-client relationship.