Updated October 7, 2026 · 8 min read
On Oct. 6, 2026, the U.S. Supreme Court heard argument in Anderson v. Intel Corp. Investment Policy Committee, a case that will decide how much a worker must show before a lawsuit over poorly performing 401(k) investments can move forward. The case began in 2019, when a former employee of Intel, the Santa Clara chip maker, sued in federal court in Northern California over how the company’s retirement committee invested workers’ savings.
The ruling will reach far beyond Intel. Most California workers with a 401(k) are in a plan governed by the same federal law. If the Court adopts a strict test, it will be harder for employees to get a fiduciary-breach case past the first motion to dismiss, before they ever see the plan’s internal records.
This post covers the argument, why federal law (not California law) controls most 401(k) disputes, where California law still protects you, and what to do now.
- The U.S. Supreme Court heard argument in Anderson v. Intel on Oct. 6, 2026, a 401(k) case first filed in federal court in Northern California in 2019.
- The question is whether workers who claim plan investments underperformed must point to a meaningful benchmark, a comparable fund that did better, just to get past a motion to dismiss.
- Justices seemed likely to keep some benchmark requirement but may limit how similar the comparison fund must be; no decision has been issued, and one is expected by summer 2027.
- Federal ERISA law, not California law, governs most private 401(k) plans, but California still protects you against retaliation and requires CalSavers access where no plan is offered.
- You have the right to request your plan documents in writing, and ERISA fiduciary claims carry strict three-year and six-year deadlines.
What happened
According to the case record summarized by Cornell Law School’s Legal Information Institute, Intel’s Investment Policy Committee changed the structure of the custom funds offered in its retirement plans after the 2008 financial crisis. It added hedge funds and private equity to the usual mix of stocks and bonds, with the stated goal of reducing volatility and limiting losses in downturns. The committee disclosed that these funds would likely trail stock-heavy funds in rising markets and would carry higher fees than passive index funds.
Former employee Winston Anderson filed a proposed class action in 2019 in the U.S. District Court for the Northern District of California. He alleged that the alternative investments were imprudent and underperformed other available funds. The district court dismissed the case, and in May 2025 the Ninth Circuit affirmed. Both courts held that the complaint failed to identify a meaningful benchmark: a comparable fund with similar goals and strategies that did better. The stock-heavy funds Anderson pointed to, the courts said, were not a fair comparison for funds built to reduce risk.
The Supreme Court agreed to hear the case on Jan. 16, 2026. In July 2026, Bloomberg Law reported that the U.S. Department of Labor filed a brief backing Intel, and the government was given time to argue alongside the company. In August, the Court let the federal government share argument time. At the Oct. 6 argument, Matt Wessler of Gupta Wessler argued for the workers, Luke McCloud of Williams & Connolly argued for the Intel committee, and an assistant to the U.S. Solicitor General argued for the United States in support of the committee.
Bloomberg Law reported that the justices seemed unwilling to let workers challenge fund performance with no comparison at all, but wary of a rule so rigid that courts would hunt for an identical twin fund. Justice Barrett raised that twin-fund concern directly, and Justice Kagan floated the idea that a comparison fund should be meaningfully similar, not identical. Justice Gorsuch told the workers’ lawyer his argument had shifted away from the question the Court agreed to decide, and Justice Kavanaugh indicated the Court would answer that question as presented. Commentators predicted the Court will keep some benchmark requirement while giving lower courts more guidance. No decision has been issued.
| Date | Event |
|---|---|
| After 2008 | Intel’s committee adds hedge funds and private equity to custom retirement funds |
| 2019 | Winston Anderson files a proposed class action in federal court in Northern California |
| May 2025 | Ninth Circuit affirms dismissal for lack of a meaningful benchmark |
| Oct. 20, 2025 | Anderson asks the Supreme Court to review the case |
| Jan. 16, 2026 | Supreme Court grants review |
| July 9, 2026 | The federal government files a friend-of-the-court brief supporting Intel |
| Aug. 17, 2026 | Court lets the government share argument time |
| Oct. 6, 2026 | Oral argument (second day of the new term) |
| By late June 2027 | Decision expected (the Court usually rules in argued cases by the end of its term) |
Video: Atlanta News First, Oct. 7, 2026 — “Supreme Court weighing 401K retirement case.”
What this means for California workers
Most private-sector 401(k) plans are governed by the federal Employee Retirement Income Security Act (ERISA). ERISA requires the people who run the plan to act prudently and solely in participants’ interest (29 U.S.C. § 1104). When they do not, participants can sue on behalf of the plan to restore losses (29 U.S.C. § 1132(a)(2)).
The fight in the Intel case is about the very first stage of that lawsuit. Workers rarely have the committee’s meeting minutes or consultant reports when they file. Those records come out in discovery, which only happens if the complaint survives a motion to dismiss. A strict benchmark rule means a case can end before workers ever see how the decisions were made.
Because California sits in the Ninth Circuit, California workers already face the benchmark requirement the Ninth Circuit applied to Intel. Some other courts, including the Sixth Circuit, have said a benchmark is useful but not always required. The Supreme Court’s ruling will set one national rule.
The case concerns claims that a plan’s investments performed badly. Claims about excessive fees or conflicts of interest raise different issues, though a broad ruling could shape how courts read those complaints too. Government plans such as CalPERS and CalSTRS are not covered by ERISA.
Your rights under federal and California law
For most workplace issues, California law is more protective than federal law, and California workers get the benefit of the stronger rule. Retirement plans are the major exception. ERISA contains a broad preemption clause (29 U.S.C. § 1144) that displaces state laws that relate to covered employee benefit plans. That means a 401(k) investment claim is a federal claim, generally filed in federal court and decided under federal standards, and California cannot impose a stricter prudence standard on private plans. Our guide to fiduciary duties under ERISA explains what plan managers owe you.
Your right to plan documents
You do not need to file a lawsuit to see how your plan works. ERISA requires the plan administrator to give you, on written request, copies of the summary plan description, the plan document, the latest annual report (Form 5500) and other governing instruments (29 U.S.C. § 1024(b)(4)). A court can impose a penalty of up to $110 a day on an administrator who fails to provide requested documents within 30 days (29 U.S.C. § 1132(c)(1); 29 C.F.R. § 2575.502c-1). Plans must also give participants annual disclosures that list each investment option’s fees and historical performance alongside a market benchmark.
Deadlines
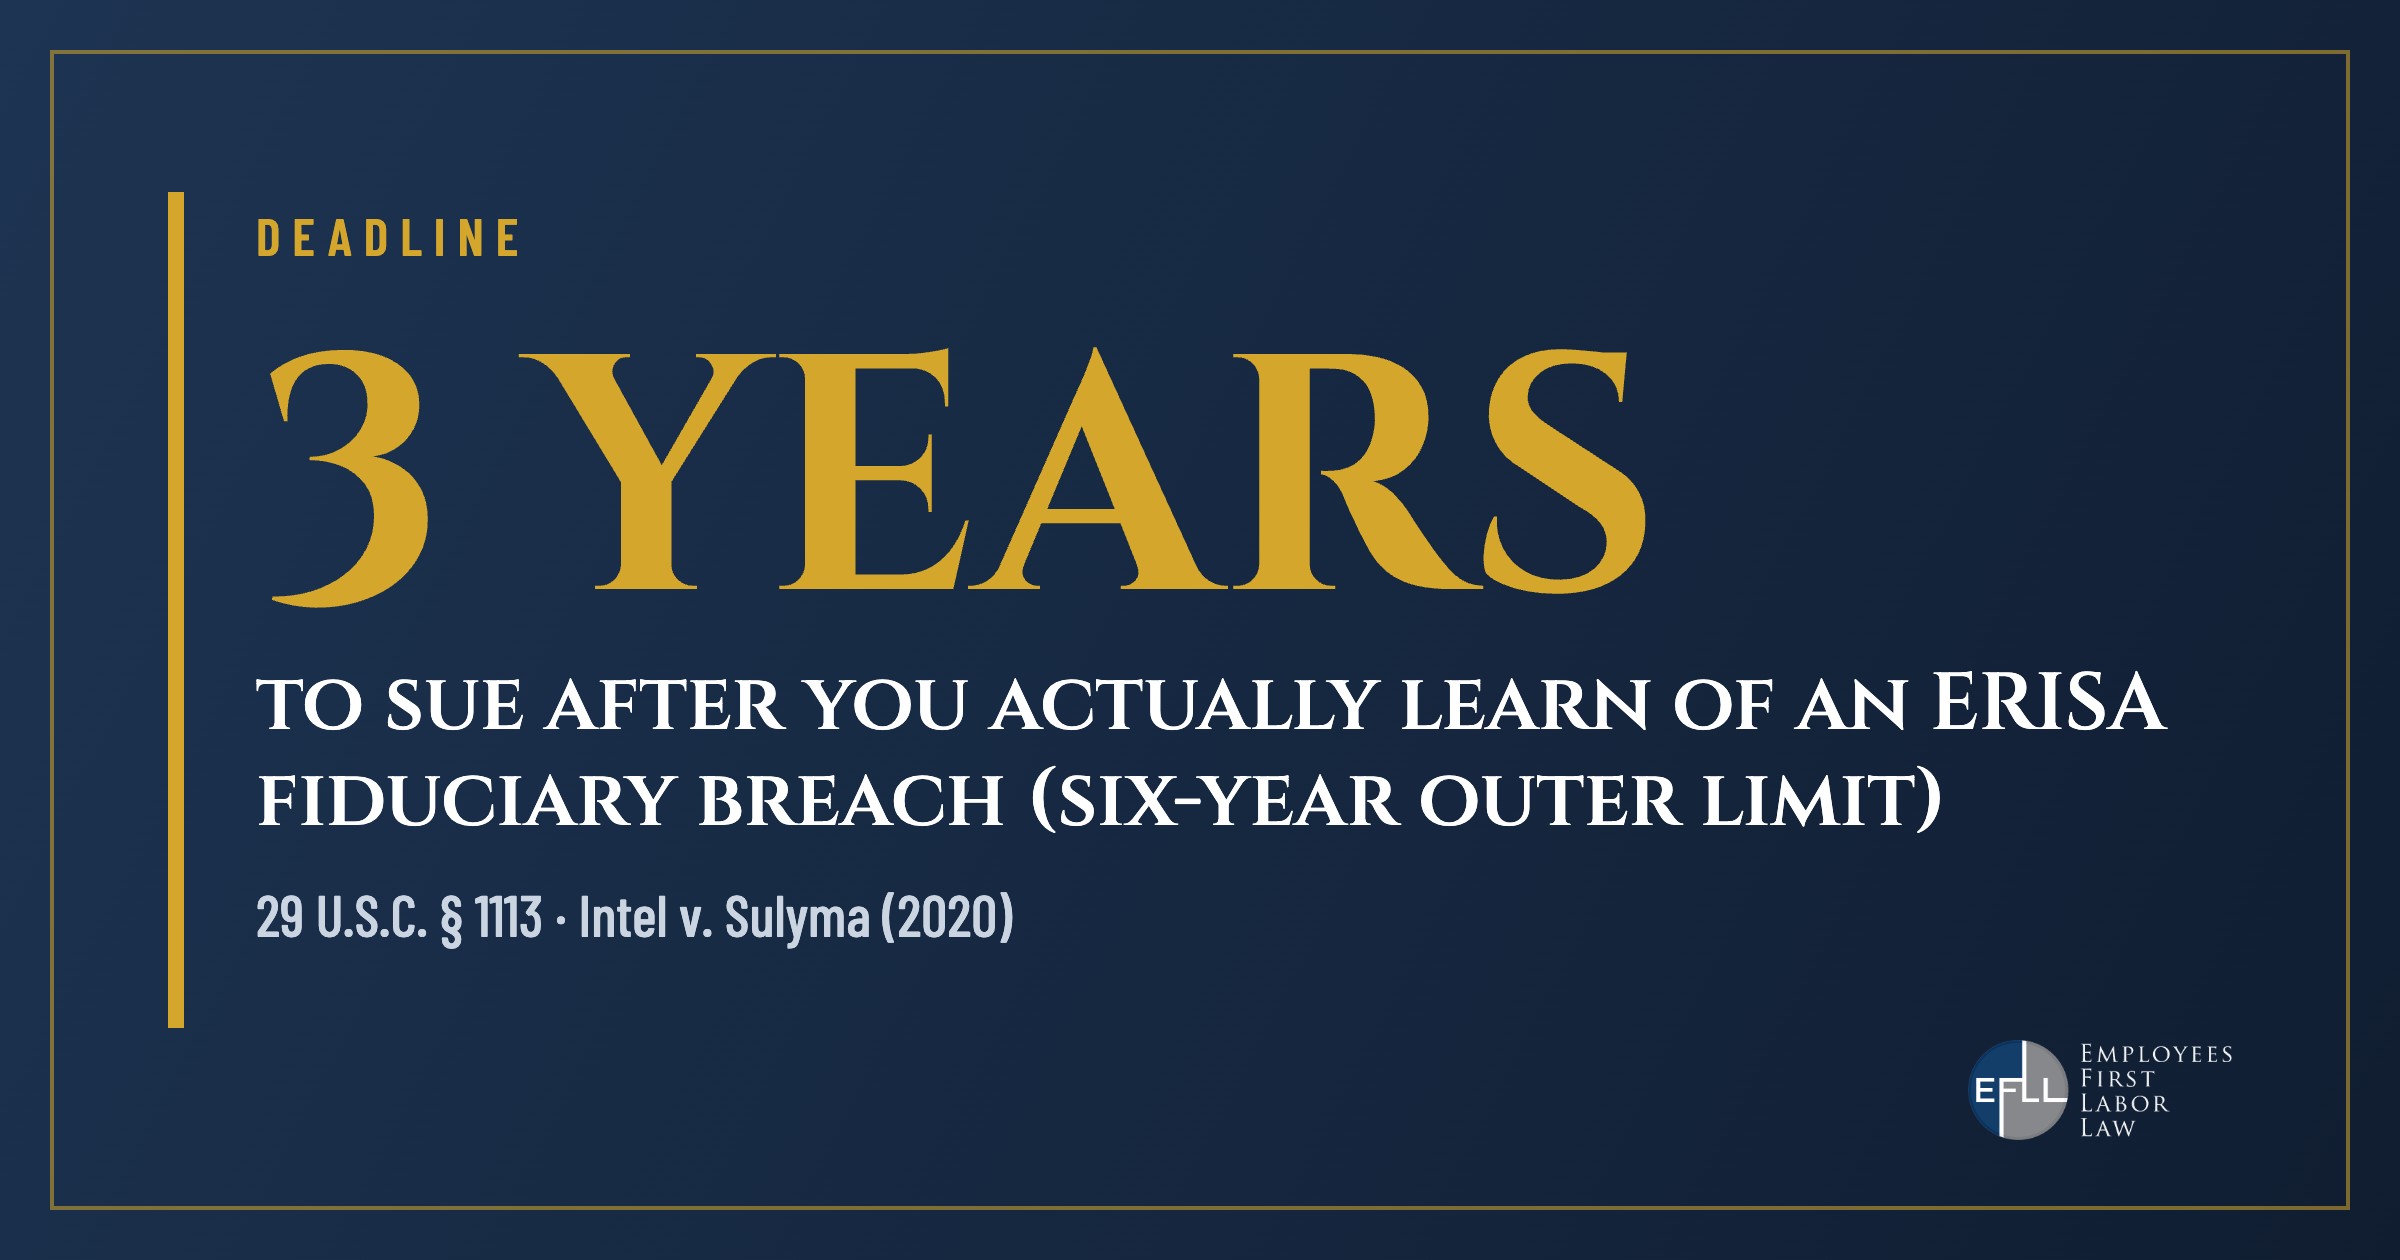
ERISA fiduciary claims generally must be filed within six years of the breach, or within three years after you actually learned of it, whichever is earlier (29 U.S.C. § 1113). If the breach involved fraud or concealment, the deadline is six years after you discover it. In a 2020 case involving the same Intel committee, the Supreme Court unanimously held that actual knowledge means real awareness, not just a disclosure you received but never read. Even so, do not wait if you suspect a problem.
Protection against retaliation
ERISA makes it unlawful to fire, discipline or discriminate against a participant for exercising plan rights, to interfere with benefits, or for giving information or testifying in an ERISA proceeding (29 U.S.C. § 1140). California adds its own protection: Labor Code section 1102.5 bars retaliation against employees who report what they reasonably believe is a violation of a state or federal law to a government agency or to someone at work with authority to investigate. If you were pushed out after raising concerns about your plan, read our guides on being fired after complaining to HR and retaliation claims in California.
Where California law fills the gap: CalSavers
California requires employers that do not offer a workplace retirement plan, now including employers with just one employee, to give workers access to CalSavers, the state-run automatic IRA (Government Code section 100000 and following). The Ninth Circuit has held that CalSavers is not an ERISA plan, so state law governs it.
Leaving your job
If you are laid off or offered severance, read the release carefully. Many separation agreements list ERISA claims among the claims you give up, while carving out benefits already vested under the plan. Our severance agreement review guide explains what to check before you sign.
Our attorneys can review your plan documents and fee disclosures and explain your options under ERISA and California law. Schedule a free consultation.
What to do now
- Read your annual fee and performance disclosure. Compare each fund’s returns with the benchmark the plan itself lists, and note funds with unusually high fees.
- Request plan documents in writing. Ask the plan administrator for the summary plan description, plan document and latest Form 5500. Keep a copy of your request and the date you sent it.
- Save your statements and note dates. Keep quarterly statements and write down when you first learned of a change in investments or fees; ERISA’s deadlines run from specific dates.
- Do not sign a release without review. If you are leaving your job, check whether the agreement waives retirement-plan claims.
- Get advice before the Supreme Court rules. A lawyer can tell you whether your concern involves investments, fees, late deposits of your contributions or a denied benefit. Learn more on our ERISA practice page.
Frequently asked questions
Does this case affect my 401(k) balance?
No. The case is about the rules for suing plan fiduciaries, not about anyone’s account balance. Your vested savings remain yours under the plan’s terms whatever the Court decides.
I work in California. Can I sue over my 401(k) under California law instead?
Usually not. ERISA preempts most state-law claims about private employer retirement plans, so fiduciary claims are brought under federal law. California law still matters for related issues, such as retaliation, wages and CalSavers.
What is a meaningful benchmark?
It is a comparison investment with similar goals, risk and strategy that performed better than the fund being challenged. The Ninth Circuit requires one when a claim rests on poor performance. The Supreme Court is deciding whether that is required and how similar the comparison must be.
When will the Supreme Court decide?
No date is set. The Court typically issues decisions in argued cases by the end of June, so a ruling is expected by summer 2027. We will update this post when it is released.
Sources
- Bloomberg Law: Justices Debate How Much 401(k) Benchmark Guidance to Give
- Bloomberg Law: Intel Gets Labor Department Backing in Supreme Court 401(k) Case
- SCOTUSblog: Justices to debate investment choices for retirement funds
- Cornell Legal Information Institute: Anderson v. Intel Corporation Investment Policy Committee
- Supreme Court of the United States: October 2026 argument calendar
- 401(k) Specialist: Anderson v. Intel Case Heads to Supreme Court Tuesday
- DLA Piper: Supreme Court to decide ERISA 401(k) pleading standard in Anderson v. Intel Corp.
Related guides
 Workers only. Never employers.

At Employees First Labor Law, we represent California workers only, never employers. Our team has recovered more than $200 million for our clients, and we prepare every case as if it is going to trial. We have offices in Pasadena, Irvine, Long Beach, Pomona, Riverside, Bakersfield and Fresno, and we serve workers throughout California. Meet our team.
If you think your retirement plan was mismanaged, or you were pushed out after raising concerns about it, we can help you understand your rights and deadlines. Employees First Labor Law represents workers only, and your first consultation is free.
- ✅ Free, confidential consultation
- ✅ We represent workers only, never employers
- ✅ Se habla español: Empleados Primero
This article provides general information about California law and is not legal advice for any specific situation. Reading it does not create an attorney-client relationship. Past results do not guarantee a similar outcome.


